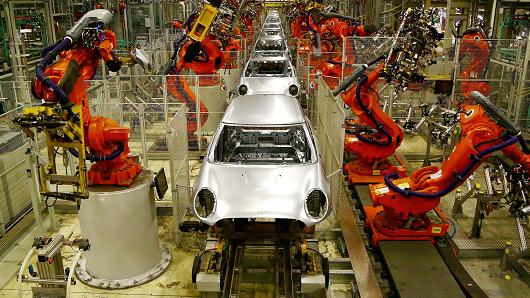
Geoff Caddick | AFP | Getty Images
Robotic arms work on the bodyshells of Mini cars as they pass along a section of automated production line at the BMW Mini car production plant in Oxford, west of London.
Why are these auto subprime defaults happening?
UBS explains that the root causes of the rise in delinquency rates can be traced back to rising U.S. consumer income inequality and aggressive easing in lending conditions, primarily from non-bank lenders. “Central bank reflation efforts have been more successful at fuelling wealth creation for a subset of the consumer and less effective in stimulating broader income growth,” according to UBS.WHowever, the global automotive wing of London-based Evercore ISI research thinks the auto lending is not the next subprime bubble.
“Third parties have flagged that auto delinquencies are at or close to record levels,” Evercore ISI’s George
But data from TransUnion points out that subprime auto lending balances total $179 billion, which is 16 percent of all auto loans outstanding. UBS estimates subprime consumer debt outstanding is $1.25 trillion – comprised primarily of
Are autos a robust asset class?
“We continue to believe that auto as an asset class is extremely robust. Not only are contracts underwritten in the knowledge that the asset’s value will depreciate but also vehicles are easy to repossess and have an intrinsic tangible value,” according to the Evercore ISI research. The note further explains that consumers tend to keep up payments and in the event that they do not, recovery can be made.