For years China’s top officials have touted their ambitious policy priority to wean the world’s second-largest economy off high levels of debt, but there is not much to show for it.
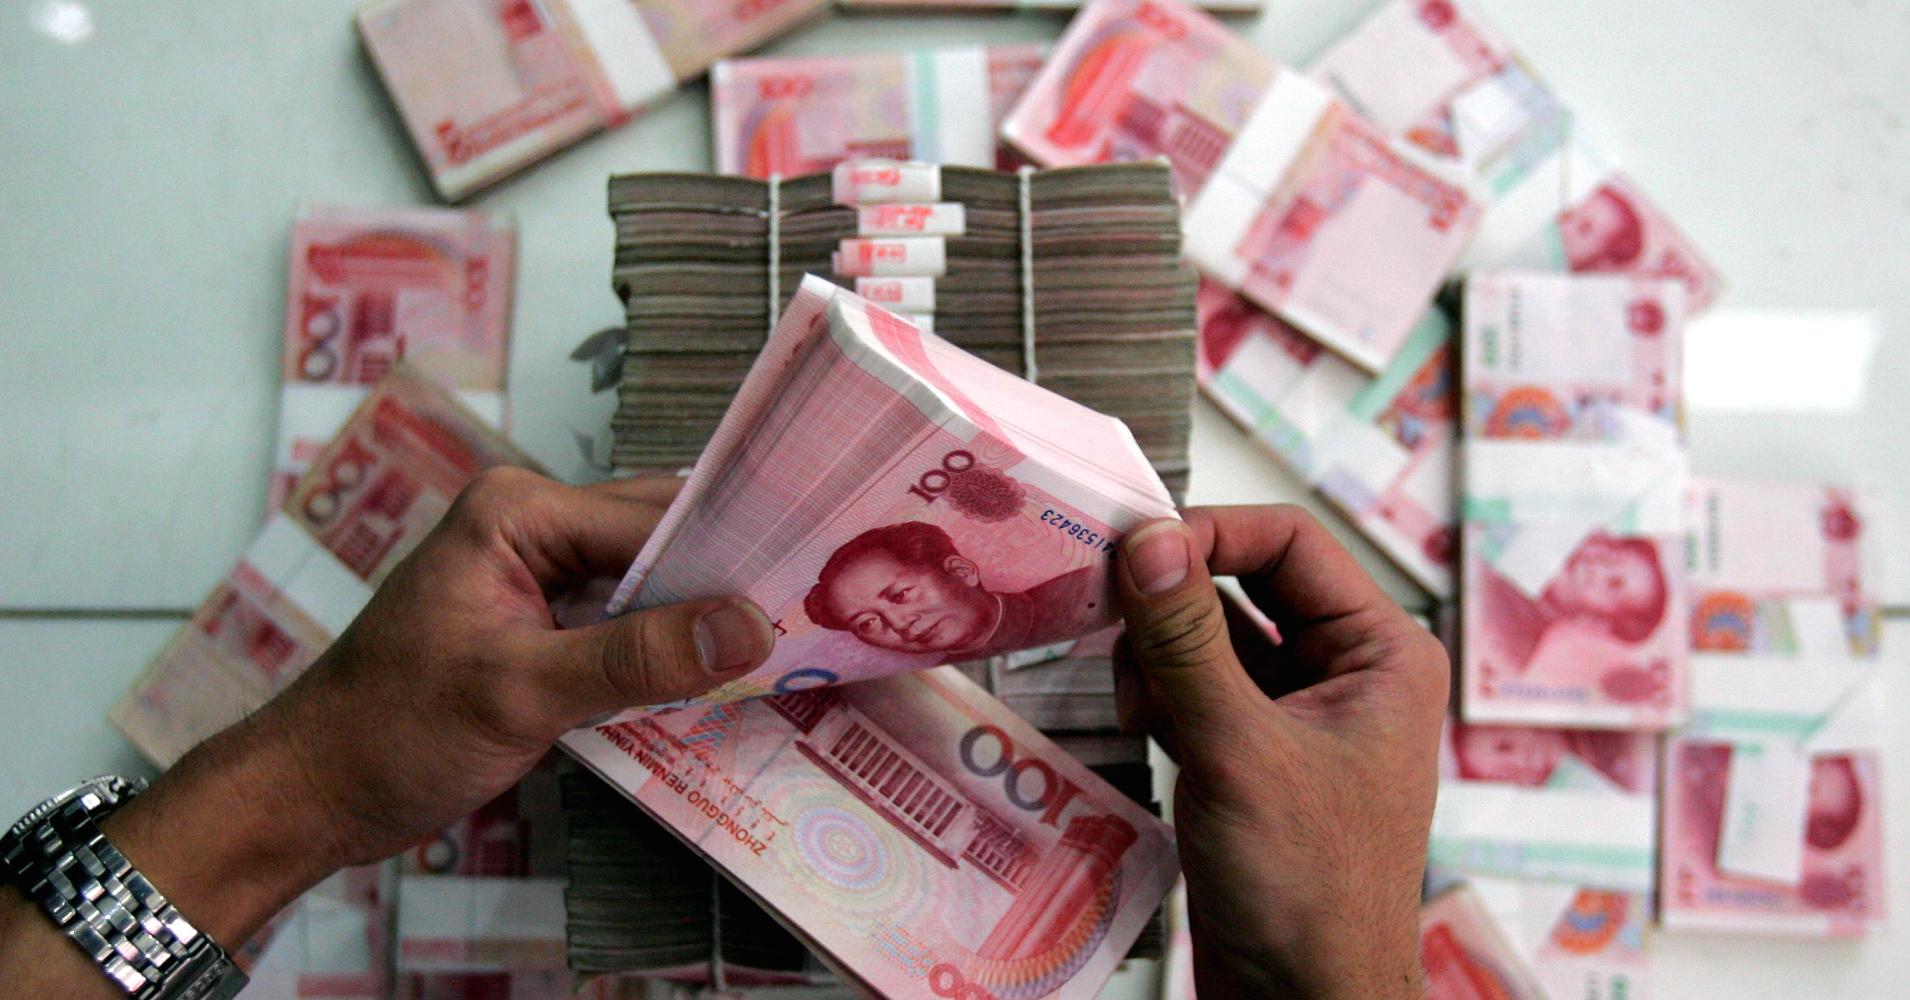
On the contrary, a Reuters analysis shows the debt pile at Chinese firms has been climbing in that time, with levels at the end of September growing at the fastest pace in four years.
The build-up has continued even as policymakers roll out a series of measures to end the explosive growth of debt, including persuading state firms and local governments to prune borrowing and tighter rules and monitoring of banks’ short-term borrowing.
By some estimates, China’s overall debt is now as much as three times the size of its economy.
Without a comprehensive strategy to tackle the overhang, there is a growing risk China will have a banking crisis or sharply slower growth or both, the International Monetary Fund said last year.
China’s central bank governor, Zhou Xiaochuan, made global headlines with a warning last month of the risks of a “Minsky moment”, referring to a sudden collapse in asset prices after long periods of growth, sparked by debt or currency pressures.
On the sidelines of a key, twice-a-decade Communist Party Congress in October, Zhou referred to relatively high corporate debt and the fast pace of growth in household lending.
While also pledging to fend off such risks, Zhou has acknowledged it will take some time to bring debt down to more manageable levels.
Reuters analysis of 2,146 China listed firms showed their total debt at the end of September jumped 23 percent from a year ago, the highest pace of growth since 2013. The analysis covered three-fifths of the country’s listed firms, but excluded financials, which have seen the brunt of government de-risking and deleveraging efforts so far.
The analysis revealed that debt in the real estate sector multiplied the most over last five years, followed by industrials.