In Shanghai, the average daily turnover in the most actively traded copper contract was about 3.02 million tons in 2016, Citi noted. In contrast, average turnover of the most actively traded copper contract on the LME in 2016 was equivalent to around 1.5 million tons of copper per day.
While investors are aware that price swings in Chinese futures are often magnified due to the sheer amount of trades going on daily, they are unable to completely shut the noise out due to the inevitable spillover into international markets.
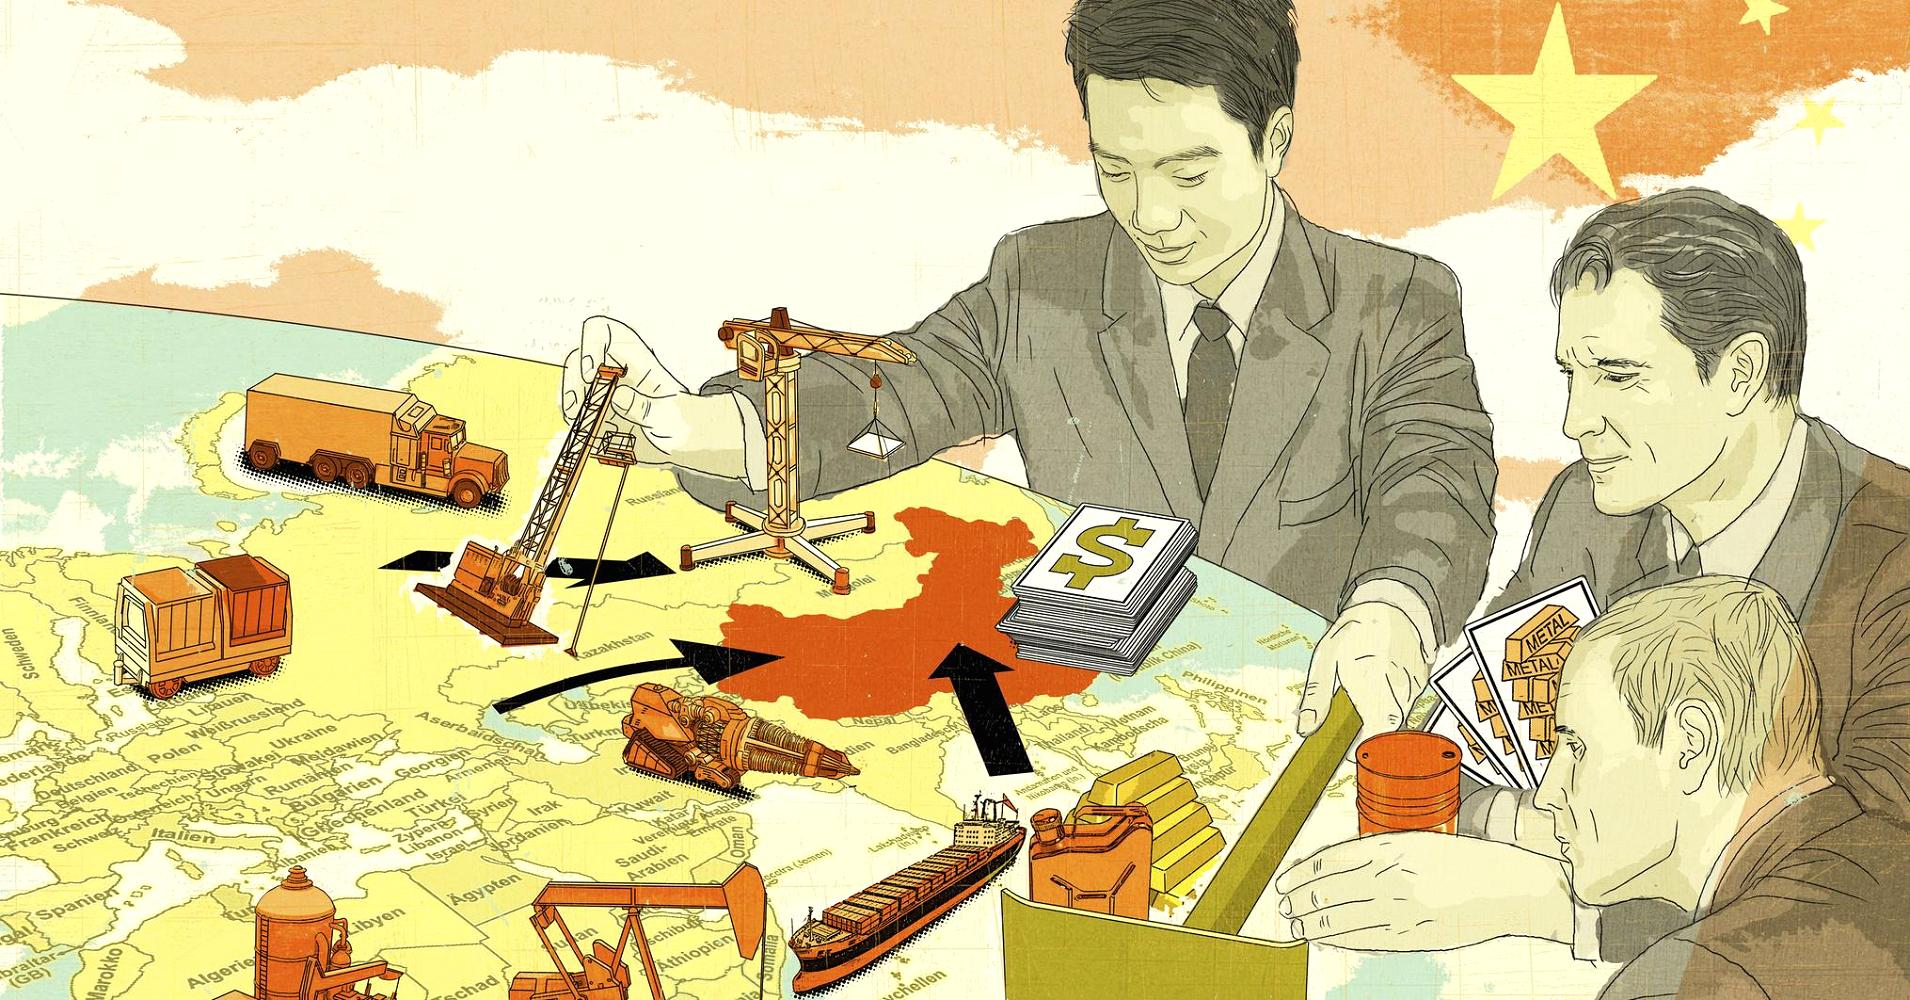
“China is playing a more and more important role in the futures trade. So far, the Chinese traders tend to be more short term-oriented and quite ‘speculative,” trader and president of Lin Asset Management, Chen Lin, told CNBC. “A lot of traders in the U.S. hate it, but it is the global trend, as China is the number-one consumer of many of these metals.”
However, there are limitations and flaws to SHFE’s lead in pricing that are worrying the market, and its activity appears to be based primarily on speculation rather than supply-demand dynamics.
“The LME copper market has good levels of liquidity at least two years forward, while in contrast, the SHFE copper market has little contract liquidity further forward than about three months,” Citi analysts wrote.
This is evidenced by the turnover of the most actively traded contact on each exchange. On the SHFE, the benchmark contract accounts for the most of the turnover, while that on the LME accounts for just 40 percent, the house added. This lack of depth in Shanghai’s trading activity makes it challenging for investors to hedge their trades.
There are other difficulties. For now, trading on Chinese commodity exchanges is still encumbered by a lack of foreign exchange convertibility and limited foreign participation due to regulations.
“The SHFE market remains very short term and local in focus, but with an increasing spillover onto levels of global volatility,” Citi added.
“This has perhaps been the most striking feature of Chinese futures markets, rather than the impact on price determination per se.”